Garage Condo Financing Options in the Denver Front Range
Updated: Aug 16
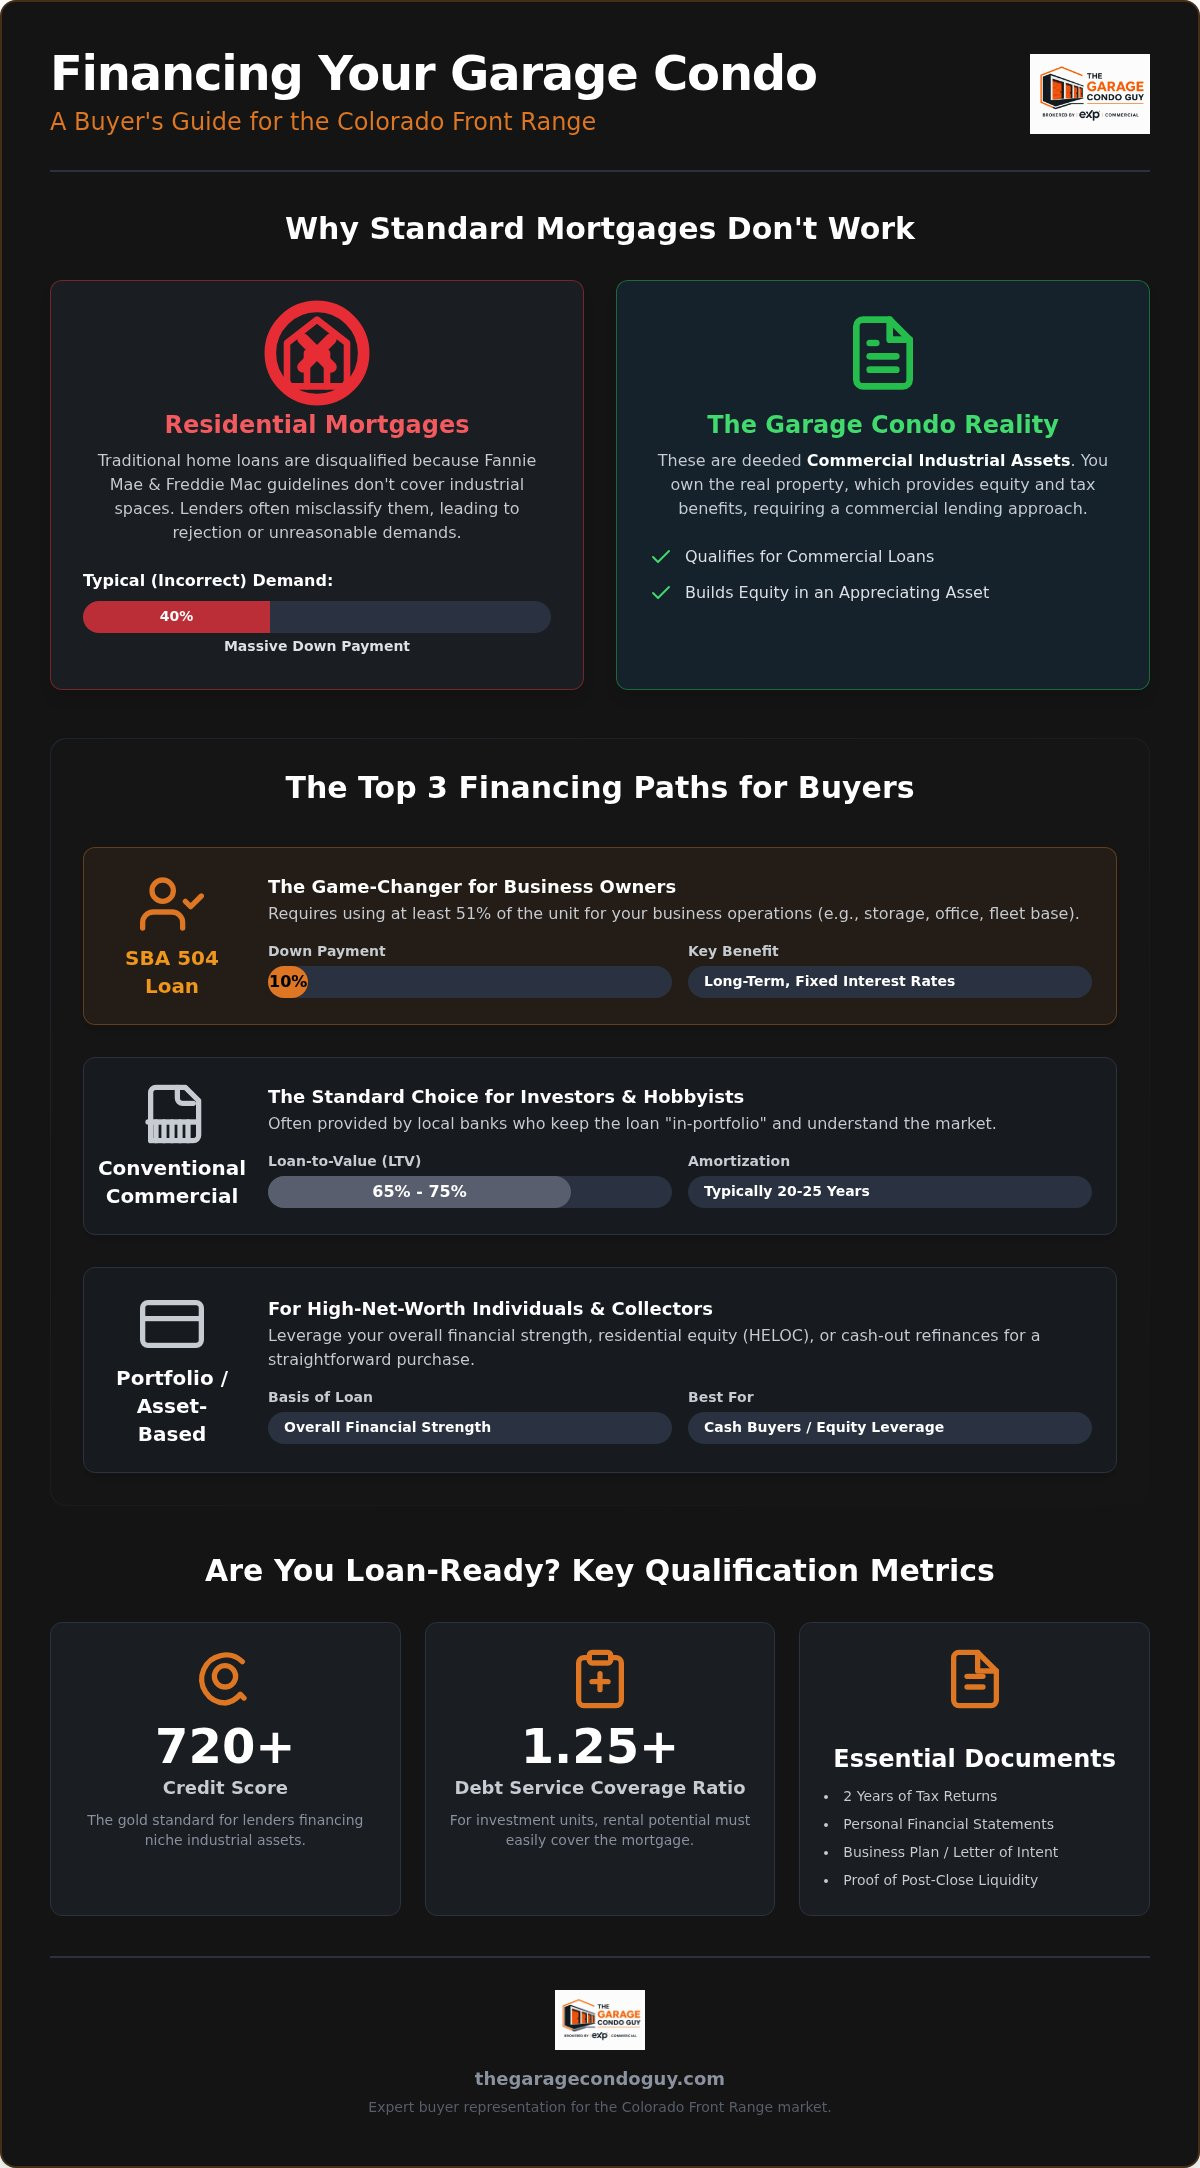
Your local bank probably thinks your dream garage condo is just a fancy backyard shed. They're wrong, and that fundamental misunderstanding is why so many applications for Financing & Loan Options for Garage Condos in the Denver Front Range hit a brick wall. Most traditional lenders try to shoehorn these units into residential categories or demand massive 40% down payments because they don't grasp the true value of the asset. It's frustrating to have the capital and the passion but no path to the closing table.
You deserve a financing partner who speaks your language. This guide will help you master the complexities of the commercial lending landscape and reveal the specific loan products that actually work for this unique property type. We'll explore why SBA 504 loans are a game-changer for owner-users and how portfolio lenders view LTV ratios for car condos. By the end, you'll know exactly how to secure a competitive deal with a lender who understands the Colorado market as well as you do.
Table of Contents
Why Standard Mortgages Do Not Work for Garage Condos
Most buyers start their journey by calling their residential loan officer. That's a mistake. Residential mortgages are built for homes where people sleep; garage condos are technically commercial or industrial condominiums. These units carry their own legal deeds. This makes them distinct real property rather than just "expensive storage units." Because Fannie Mae and Freddie Mac don't include industrial flex space in their guidelines, traditional home loans are off the table.
Your intended use case dictates the Financing & Loan Options for Garage Condos you can access. Are you running a small business, storing a high-value car collection, or seeking a pure real estate investment? Lenders evaluate these assets based on their income potential or business utility. This isn't a simple home improvement project; it's a strategic acquisition of an appreciating industrial asset.
The Deeded Difference
When you buy a garage condo, you aren't just renting a box. You own the dirt and the air space within your unit. This ownership structure changes the lending math entirely. Unlike traditional self-storage where you're a tenant at the mercy of a landlord, owning a deeded unit provides equity and tax benefits. Lenders see this as a stable, long-term commercial play.
Why Local Banks Often Win
National lenders often struggle to appraise niche industrial assets in cities like Denver or Boulder. Local Front Range banks win because they keep loans in-house as portfolio products. These institutions understand the specific market demand for car condos and appreciate the true value of a deeded industrial unit better than any out-of-state underwriter. If you're hitting dead ends with big banks, reach out to The Garage Condo Guy to find a lender who gets it.
The Top 3 Financing Paths for Colorado Buyers
Securing the right capital requires matching your specific profile to the correct lender. You have three primary Financing & Loan Options for Garage Condos in the Front Range. First, conventional commercial loans remain the standard choice. These typically offer LTV ratios between 65% and 75% with 20 to 25 year amortization schedules. Second, the SBA 504 program allows business owners to preserve cash by putting as little as 10% down. Finally, many buyers leverage residential equity through HELOCs or cash-out refinances to fund their purchase. As we look at 2026 interest rate trends, locking in fixed rates early is becoming essential to manage monthly carry costs effectively.
SBA 504: The Small Business Secret
If you use at least 51% of your unit for business operations, the SBA 504 loan is your best friend. This includes using the space for equipment storage, a professional office, or a base for your service fleet. You get the benefit of long-term fixed rates. This provides incredible stability for your business overhead while you build equity in a premium industrial asset. If you aren't sure if your business qualifies, speaking with an expert can clarify your eligibility quickly.
Portfolio Lending for Collectors
High-net-worth individuals often skip traditional channels entirely. Asset-based lending allows you to secure a unit based on your overall financial strength rather than just the property income. Because these deals are specialized, you need a Front Range garage condo specialist to open doors at the right banks. These lenders understand that a car collection isn't just a hobby; it's a valuable lifestyle investment that deserves professional backing. They look at the big picture of your portfolio to find a structure that works for your unique situation.
Qualifying for Your Loan: Requirements and Ratios
Commercial lenders demand more than just a steady paycheck. They want to see a 720+ credit score. This is the gold standard for niche industrial assets. If you're eyeing an investment unit, the Debt Service Coverage Ratio (DSCR) takes center stage. Lenders usually look for a ratio of 1.25 or higher. They need to know the unit’s rental potential easily covers the mortgage. Don't forget about post-close liquidity. Banks want to see cash in your account after the down payment is gone. They need to know you're stable.
The appraisal hurdle is often the biggest deal-killer. Finding accurate comps in Denver, Lakewood, or Superior requires local expertise. These aren't standard warehouses. They're premium assets that require a specialized valuation. A generic appraiser will miss the mark. You need a lender who understands why these units command a premium.
Essential Documentation Checklist
Underwriting is deep. You'll need personal financial statements and two years of tax returns ready to go. Even for personal hobby storage, a simple "Business Plan" or letter of intent helps. It defines your use case for the bank and eliminates guesswork. This clarity is vital when navigating Financing & Loan Options for Garage Condos. It moves your file from the "maybe" pile to the "approved" pile.
Understanding Loan-to-Value (LTV)
Expect to bring more cash to the table. Garage condos usually require 25% to 35% down. This is a commercial play, not a residential one. Lenders mitigate their risk by requiring higher equity. Fortunately, the rising resale value of Colorado garage condos keeps lender confidence high. Ready to find out which program fits your balance sheet? Reach out to Ryan to get your pre-approval started.
How to Secure Financing in the Front Range Market
Attempting to "go it alone" with a standard residential loan officer is a high-risk move. These professionals excel at home mortgages, but they often struggle with the industrial flex space category. You need a partner who identifies "lender-friendly" projects in cities like Longmont and Dacono. These specific developments frequently have existing relationships with banks that already understand the asset's value. This specialized knowledge prevents your application from getting stuck in a cycle of endless residential-style questions that don't apply to commercial deeds.
Closing the deal requires precision and speed. You must navigate environmental reports, specifically Phase I assessments, and conduct a rigorous review of the condo association (HOA) documents. These steps are non-negotiable for commercial lenders. Timing is everything in the Colorado market. With 2026 shaping up to be a year of price escalation for industrial assets, securing your Financing & Loan Options for Garage Condos today is vital. It allows you to beat the next wave of appreciation.
The Role of the Specialist
Ryan provides the expert guidance necessary to navigate the specific nuances of the Front Range. He excels at linking buyers with the right lenders for car storage investment opportunities. This isn't just about finding a rate; it's about finding a lender who won't flinch at the unique nature of a car condo. Having a dedicated advocate ensures your documentation is polished and your file stays at the top of the underwriter's desk.
Take the Next Step
Don't let financing hurdles stop your search for the ultimate car or RV sanctuary. The right capital is available if you know where to look. Take control of your investment journey right now. Contact The Garage Condo Guy today for a curated list of lenders and available units.
Secure Your Front Range Asset Today
Owning a premium garage condo in Denver or Boulder is a lifestyle upgrade and a savvy industrial investment. You now understand that these deeded properties require a commercial approach rather than a standard home mortgage. Success depends on choosing the right Financing & Loan Options for Garage Condos; whether you utilize an SBA 504 loan for your business or a portfolio product for your private collection. The hurdles of high LTV ratios and niche appraisals shouldn't stop your progress.
Ryan specializes in the Front Range market and maintains a deep network of lenders who specifically understand this asset class. Don't waste time with generalists who don't grasp the value of a deeded hobby shop. Take the definitive step toward securing your space. Get Expert Financing Guidance for Your Colorado Garage Condo and turn your vision into a closed deal. Your ideal car or RV sanctuary is well within reach.
Frequently Asked Questions
Can I get an FHA or VA loan for a garage condo?
No, you cannot use FHA or VA loans for these properties. Those programs are strictly reserved for residential primary residences. Since garage condos are deeded as commercial or industrial assets, they don't qualify for government backed residential programs. You'll need to explore commercial Financing & Loan Options for Garage Condos instead. This ensures you're working within the correct asset class from day one.
What is the typical down payment for a car condo in Colorado?
Expect to put down 25% to 35% for a conventional commercial loan. Lenders require higher equity for niche industrial assets compared to residential properties. However, if you're a small business owner using the space for operations, an SBA 504 loan could lower that requirement to just 10%. This flexibility helps you keep more capital in your business while still securing a premium Front Range location.
Are garage condo interest rates higher than home mortgage rates?
Yes, commercial interest rates are typically 0.5% to 2% higher than standard 30 year fixed residential mortgages. Banks view commercial lending as higher risk, which is reflected in the pricing. These loans also often feature shorter fixed rate periods or balloons after 5 to 10 years. Understanding these Financing & Loan Options for Garage Condos helps you calculate your true monthly carry costs accurately before signing.
Can I use my 401(k) or IRA to finance a garage condo purchase?
You can use a self directed IRA (SDIRA) or a 401(k) loan to fund your purchase. An SDIRA allows you to hold real estate as an investment, but you cannot use the space for personal storage. If you need the unit for personal use, taking a loan against your 401(k) might be a better path. Always consult with a tax professional to ensure you avoid prohibited transaction penalties.
Does the garage condo association (HOA) affect my ability to get a loan?
Your lender will perform a deep dive into the association's health. They look for adequate cash reserves, proper master insurance coverage, and a lack of pending litigation. If the HOA is poorly managed or underfunded, the bank may deny the loan regardless of your credit score. Reviewing these documents during your due diligence period is essential to ensure the project meets commercial lending standards.
Comments